



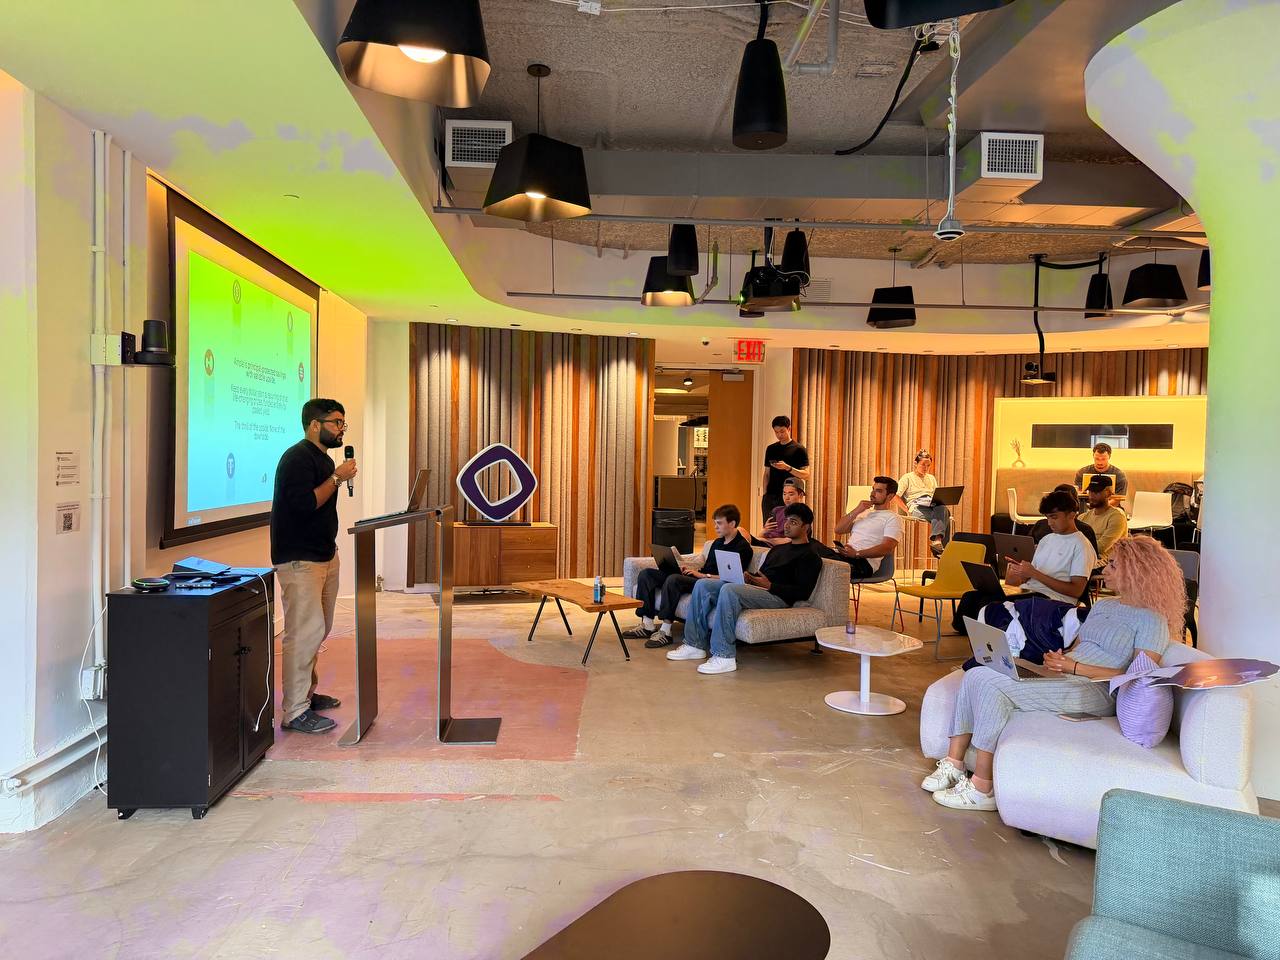
As the creator and product lead of Ample, Patel has made risk language, public verification, and deliberate restraint part of the product-design process itself.
Two phrases Zeel Patel did not want attached to a savings product were “guaranteed” and “risk-free.” Patel, Head of Product at Layer3 and creator of its consumer savings product Ample, was trying to make a complicated financial mechanism easier to use without making it sound safer than it was. On Ample, that included a hard internal rule against calling the product “guaranteed” or “risk-free.” The language surrounding the product had to describe what customers could verify, what remained uncertain, and where risk still existed.
“Making something simple should not mean making the uncomfortable parts disappear,” Patel said. “If a customer can understand what the product does but cannot understand what could go wrong, you have simplified the wrong thing.” His approach grew out of several years working on blockchain-based consumer products, where technical complexity can disappear behind a polished interface even though the financial consequences remain with the person using it.
What a Financial Product Refuses to Promise
Patel describes financial language as part of the product mechanism itself. If a contract behaves one way, the interface suggests something different, and the marketing creates another impression, he believes the product has already failed even if the underlying software functions correctly. That principle affected how the team described Ample’s structure and the risks associated with using blockchain-based financial infrastructure.
“The words matter because people make decisions with them,” Patel said. “You cannot build one level of risk into the mechanism and then communicate a softer version of it in the interface.” For Patel, precise language is part of the work of building a consumer financial product, not something separate from the product itself.
Ample uses yield generated by deposited assets to fund recurring rewards while leaving the deposited balance intact. Patel’s approach also requires the product to acknowledge that the underlying structure still carries smart-contract and market risks.
A product can make the mechanism easier to understand without pretending the mechanism eliminates uncertainty. “If we know there is a risk, I would rather explain it clearly than find a phrase that makes the customer feel better about it,” Patel said. “The goal is informed use, not reassurance for its own sake.”
Verification Is Different From Safety
That philosophy extends to one of the most common assumptions Patel sees in blockchain-based finance: that transparency automatically makes a product safe. He rejects that shortcut.
Public infrastructure can make balances, transactions, and rules more inspectable. It cannot guarantee that a smart contract will never fail, that markets will remain stable, or that an asset will retain its value. Patel argues that transparency gives consumers better evidence with which to evaluate a financial product, but it does not remove the need for judgment.
“Being able to inspect something is valuable, but inspection is not the same as protection,” Patel said. “Public data can show balances and recorded transactions. It cannot turn a risky structure into a risk-free one.”
Ample was designed so deposits, balances, and reward payouts can be inspected through public infrastructure. The product also underwent an independent security audit by Pashov Audit Group in December 2025. Approximately $4.66 million is held across seven networks, with the amount independently tracked by DeFiLlama.
Those verification points matter to Patel because they give customers information that does not depend solely on the company asking to be trusted. He does not present an audit or a public ledger as proof that nothing can fail. Instead, he treats them as ways to make more of the product’s operation available for scrutiny.
Simplicity Moves Responsibility Somewhere Else
Making a financial product easier to use creates another problem that Patel believes product teams sometimes overlook. He describes simplicity as expensive because a one-click experience can require months of work involving routing, accounting, security, and failure handling. The fewer decisions a customer has to make, the more carefully the product team has to make them behind the scenes.
“When you take a decision away from the customer, the team inherits it,” Patel said. “That should raise the standard for the decision, not lower it.” That principle shapes how Patel evaluates the details customers no longer have to manage themselves.
That idea has influenced how Patel thinks about the line between useful abstraction and concealment. A saver should not need to understand every routing step underneath a transaction. Patel believes the same saver should still be able to understand where a return comes from and what remains exposed to risk.
Building for People Who Have Reasons to Be Skeptical
Patel is building Ample in a financial environment where consumers have seen intermediaries fail and have learned to ask harder questions about where returns come from. He says that history changes the burden on anyone designing a new savings product. Customers have reasons to ask where their money sits, what generates the return, and what assumptions are buried beneath an attractive interface.
His answer is not to ask consumers for more faith in technology. It is to expose enough information that they have something concrete to evaluate.
“I would rather build a product someone can question than one that depends on them believing us,” Patel said. “Trust is stronger when the customer has something they can check.”
That approach makes restraint part of Patel’s product philosophy. Ample still has to be usable enough that a customer does not need specialist knowledge to navigate it, but Patel does not believe ease of use should erase the financial reality underneath. The difficult design problem is deciding which complexity the product should absorb and which information the customer still needs to see.
For Patel, that is where consumer finance becomes more than an interface problem. A product can make the machinery almost invisible. The obligations attached to handling someone else’s money cannot disappear with it.