



When it comes to areas prone to various kinds of fluctuations, as real estate is, patience can be both a virtue and a vice. When it comes to waiting for lower mortgage rates, industry expert Mark Steven Fisher warns that time might not always be on your side. The complex interplay between home values, mortgage rates, and market demand has far-reaching implications for prospective homeowners and investors.
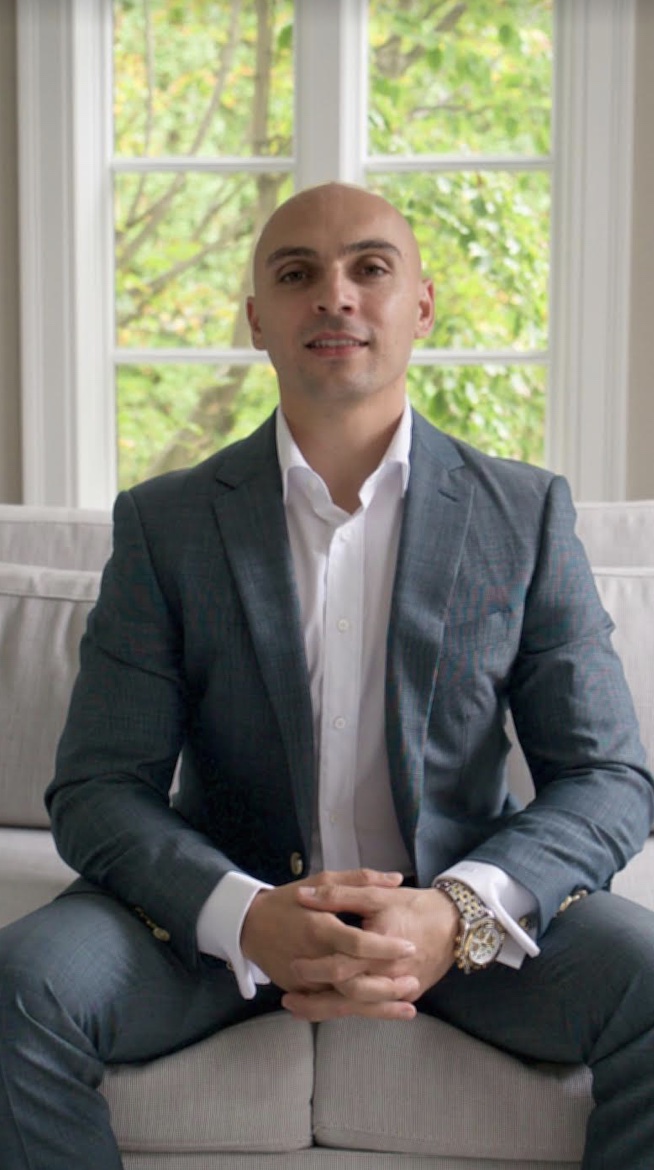
Mark Steven Fisher is a respected voice in the real estate industry with a keen understanding of the complexities of the market derived from years spent navigating property investments, market cycles, and economic fluctuations. He has assisted over 2,000 families on their path to homeownership, managing over $1 Billion in closed loan volume.
According to Fisher, fluctuations in mortgage rates significantly impact real estate demand. “I’ve seen demand recently substantially impacted as mortgage rates move up,” he says. Demand noticeably spikes as rates decline, even by as small a margin as a quarter percent. The inverse is also true – demand drops off as rates inch higher.
However, Fisher is quick to point out that the current state of the market adds another layer of complexity to this situation. With housing inventory at historic lows, the influx of buyers rushing in to take advantage of any lowering rates may face a shortage of available properties. This surge in demand, coupled with limited supply, is likely to exert upward pressure on home prices.
In a market landscape characterized by insufficient inventory, the anticipated return of sidelined buyers could exacerbate price escalations. “Once rates go down, which I predict happening later this year, you’re going to have a huge number of buyers on the sidelines come back into the market,” Fisher anticipates. But he cautions, “There’s not enough inventory. So now you have even more demand because rates are lower. But still limited inventory. So it’s going to keep pushing prices higher.”
Against this backdrop, Fisher urges potential buyers to weigh the actual savings of a lower rate against the possible cost of rising home prices. “If you’re waiting for rates to go lower, you assume you will be saving money. Unfortunately, if you’re paying a lower rate in two years but paying a higher price, you’re not saving anything.”
Adding a historical perspective to his argument, Fisher notes that over the past 80 years, home prices have increased 73 times. On average, home values typically appreciate by about 4% per year. “So if you wait two years, you’re going to be paying 8% higher, so you’re not saving anything versus if you just find something with a payment doable for you. You can always refinance once rates go lower and take advantage instead of trying to time the market,” Fisher advises.
In a market rife with uncertainties, Fisher’s insights underscore the importance of understanding the bigger picture. In the balancing act between mortgage rates and home values, waiting for the perfect moment could come at a cost. As home prices continue their upward march, the anticipated savings from lower mortgage rates may prove elusive, highlighting the potential cost of waiting in an ever-evolving real estate market.